
Best Savings Account Types: A 2026 Guide to Maximizing Your Money
 Oct, 4 2026
Savings Account Yield & Comparison Calculator
Enter your savings details below to compare how different account types perform over time. This tool uses average 2026 market rates.
| Account Type | Avg APY | Total Interest Earned | Final Balance | Recommendation |
|---|
Best Match Analysis
You’ve saved up some cash. Great. Now what? Do you leave it in your checking account where it earns pennies? Or do you lock it away for five years hoping the interest beats inflation? The truth is, there isn’t one single "best" savings account that works for everyone. It depends entirely on when you need the money and how much risk you’re willing to tolerate with your liquidity.
Most people make the mistake of treating all savings the same. They dump their emergency fund into a long-term Certificate of Deposit (CD) and panic when their car breaks down because they can’t access the cash without a penalty. Or they keep their vacation fund in a standard checking account, losing purchasing power every month to inflation. To fix this, you need to match the right type of account to the specific job that money needs to do.
Understanding the Core Trade-Offs
Before we pick winners, let’s look at the three levers you can pull: Interest Rate, Accessibility, and Minimum Balance. You generally can’t have all three at once. High-yield accounts often require higher minimums or limit withdrawals. Standard accounts offer easy access but pay almost nothing. Certificates offer great rates but lock your hands behind your back.
| Account Type | Typical APY (Oct 2026) | Access to Funds | Best For |
|---|---|---|---|
| High-Yield Savings Account (HYSA) | 4.5% - 5.2% | Easy (Online transfer takes 1-3 days) | Emergency funds, short-term goals |
| Certificate of Deposit (CD) | 4.8% - 5.5% | Locked until maturity | Known future expenses (e.g., tuition in 2 years) |
| Money Market Account (MMA) | 4.0% - 4.8% | Moderate (Checks/debit card available) | Large balances needing some liquidity |
| Traditional Savings | 0.01% - 0.10% | Instant (Branch access) | Convenience over return |
The Workhorse: High-Yield Savings Accounts (HYSA)
If you only open one new account today, make it a High-Yield Savings Account. These are typically offered by online-only banks like Marcus by Goldman Sachs, Ally Bank, or Discover. Because these institutions don’t have expensive brick-and-mortar branches, they pass those savings on to you in the form of higher interest rates.
Why choose an HYSA? Speed and flexibility. In 2026, many top-tier HYSAs offer Annual Percentage Yields (APY) hovering around 5%. Compare that to the national average of roughly 0.4% for traditional banks, and the difference is stark. On $10,000, you’d earn about $500 a year versus $40. That’s enough for a nice dinner out or a utility bill.
But there’s a catch. While federal regulations no longer strictly limit you to six withdrawals per month (Regulation D was amended), most banks still impose their own limits or fees if you withdraw too frequently. Also, moving money from an online bank to your primary checking account isn’t instant. It usually takes one to three business days via ACH transfer. This makes HYSAs perfect for money you don’t need *today*, but might need *next week*.
The Locked Box: Certificates of Deposit (CDs)
A Certificate of Deposit is essentially a time deposit. You agree to leave your money with the bank for a fixed period-three months, one year, five years-and in exchange, they guarantee you a specific interest rate.
This is the best option if you know exactly when you’ll spend the money. Say you’re saving for a wedding in 18 months. You don’t need daily access to that cash. By locking it in an 18-month CD, you protect yourself from the temptation to spend it, and you often get a slightly higher rate than an HYSA. If rates rise during your term, however, you’re stuck with your lower rate unless you use a special type called a Bump-Up CD.
Be careful with early withdrawal penalties. Most CDs charge you several months’ worth of interest if you break the contract early. If you put $5,000 in a 5-year CD with a 5% penalty and withdraw after two years, you could lose a significant chunk of your principal. Only use CDs for money you are absolutely certain you won’t touch before the maturity date.
The Hybrid: Money Market Accounts (MMAs)
People often confuse Money Market Accounts with Money Market Mutual Funds. They are different animals. An MMA is a bank account insured by the FDIC, just like a savings account. A mutual fund is an investment product that carries risk.
MMAs are interesting because they often come with check-writing privileges and debit cards. This blurs the line between spending and saving. Historically, MMAs paid higher rates than regular savings, but in the current economic climate, the gap has narrowed. Many HYSAs now pay as much or more than MMAs.
So why use an MMA? Convenience for large sums. If you have $50,000 sitting around and want to write checks directly from that pool for property taxes or contractor payments, an MMA saves you the hassle of transferring funds to checking first. However, watch out for tiered rates. Some MMAs only pay their advertised high rate if you maintain a balance above $25,000 or $50,000. Below that threshold, your rate drops significantly.
The Trap: Traditional Brick-and-Mortar Savings
Unless you live in a rural area with limited internet access or you absolutely hate digital banking, traditional savings accounts at big national banks are often a poor choice for growing wealth. The convenience fee is steep: you sacrifice nearly all potential earnings for the ability to walk into a branch.
With rates often below 0.10%, your money is effectively losing value against inflation. If inflation is 3% and your bank pays 0.05%, you’re losing 2.95% of your purchasing power annually. It’s better to link your traditional checking account to an external HYSA. Set up automatic transfers so your paycheck gets split, sending the bulk of your savings to the high-yield account while keeping a small buffer in your local checking account for bills.
How to Choose: A Decision Framework
Don’t overcomplicate it. Ask yourself these three questions:
- When do I need this money? If it’s less than 6 months, stick to an HYSA. If it’s 1-5 years, consider a CD ladder.
- Do I need to write checks? If yes, look at MMAs. If no, ignore them.
- Is my balance under $10,000? Stick to HYSAs with low minimums. Avoid accounts with maintenance fees that eat your interest.
For most people in 2026, the ideal setup involves two accounts: a local checking account for daily transactions and a separate, online HYSA for emergency funds and short-term goals. This separation creates psychological friction-it’s harder to spend money you can’t see in your immediate banking app.
Maximizing Returns in 2026
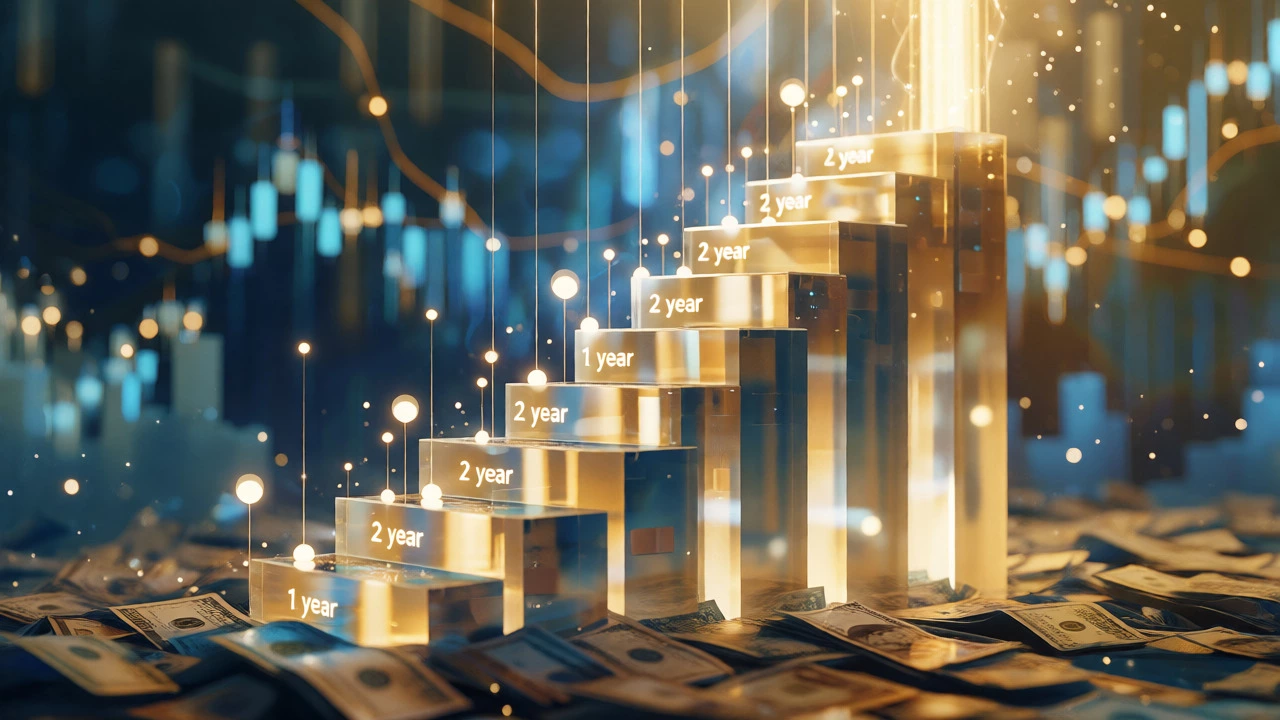
Interest rates fluctuate. When the Federal Reserve cuts rates, HYSA yields drop quickly. When they hike rates, they go up slowly. To protect your returns, consider a "CD Ladder." Instead of putting all your extra cash into one 5-year CD, split it into five chunks. Buy a 1-year, 2-year, 3-year, 4-year, and 5-year CD. Every year, one matures. You can then reinvest that matured portion into a new 5-year CD at whatever the current rate is. This strategy averages out your interest rates and provides annual access to some of your cash.
Also, keep an eye on promotional offers. Banks often compete for new customers by offering bonuses for opening accounts with a minimum deposit. While these bonuses aren’t huge (usually $100-$300), they add up if you’re disciplined enough to move money around occasionally. Just read the fine print regarding how long you must keep the money deposited to earn the bonus.
Are savings accounts safe?
Yes, provided the bank is FDIC-insured (or NCUA-insured for credit unions). This insurance protects deposits up to $250,000 per depositor, per insured bank, for each account ownership category. Even if the bank fails, you won’t lose your insured funds.
What is the difference between APY and APR?
APR (Annual Percentage Rate) is the simple interest rate. APY (Annual Percentage Yield) includes the effect of compounding interest. Because interest earns interest, APY is always higher than APR. When comparing savings accounts, always look at the APY to understand your true return.
Can I lose money in a savings account?
You cannot lose your nominal principal in an FDIC-insured savings account. However, you can lose purchasing power if inflation exceeds your interest rate. For example, if your account pays 4% but inflation is 5%, your real return is negative 1%.
Should I keep my emergency fund in a CD?
Generally, no. Emergency funds need to be accessible immediately. If you put your entire emergency fund in a CD and face a sudden medical bill, you may face early withdrawal penalties that reduce your available cash. Keep emergency funds in a High-Yield Savings Account for quick access.
Do I have to pay taxes on savings interest?
Yes, interest earned on savings accounts is considered taxable income by the IRS. You will receive a Form 1099-INT from your bank if you earn more than $10 in interest during the tax year. This applies regardless of whether the account is an HYSA, CD, or MMA.